

What the Medicare 3-Month Rule Really Means
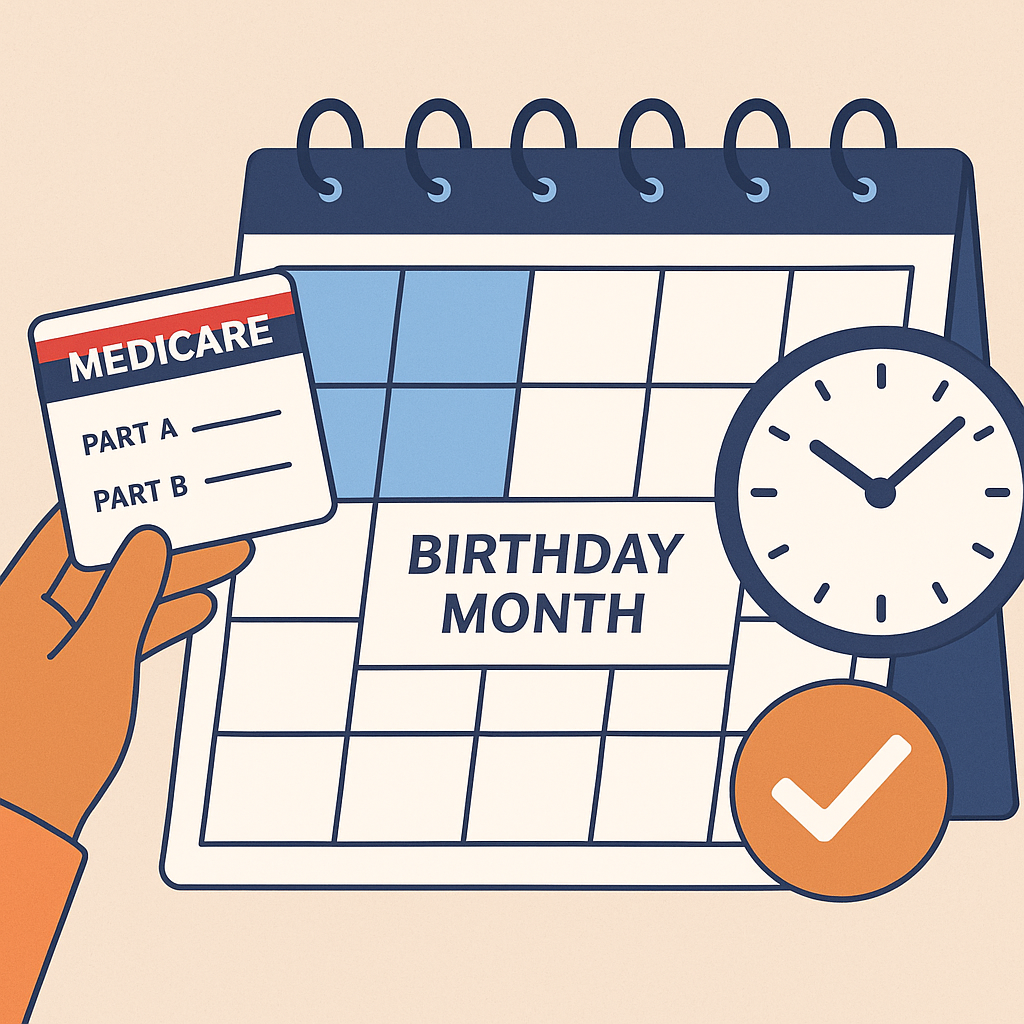
When people talk about the "3 month rule" for Medicare, they are usually referring to the first 3 months before your 65th birthday month. This window is part of a larger stretch of time called your Initial Enrollment Period, which gives you a total of 7 months to sign up for Medicare without penalty.
It helps to know that "3 month rule" is not an official term used by the Centers for Medicare & Medicaid Services. It is shorthand that many people use when trying to make sense of a timeline that can otherwise feel confusing.
Once you understand how this window fits into your broader enrollment period, the pressure of wondering whether you are acting at the right time tends to ease. You will know exactly where you stand and what your options look like.
Key Takeaways
The "3 month rule" refers to the first 3 months of your 7-month Initial Enrollment Period, the window before your birthday month. Enrolling in that early window typically starts your coverage on the 1st day of your birthday month, avoiding any gap. Mark your personal enrollment window as soon as you know your birthday month, and consider speaking with a licensed Medicare agent to confirm your exact dates.
Key Takeaways
- The '3 month rule' is not an official CMS term, it refers to the first 3 months before your birthday month within Medicare's Initial Enrollment Period
- Your full Initial Enrollment Period spans 7 months: 3 months before, your birthday month, and 3 months after
- Enrolling in the early 3-month window typically starts coverage on the 1st day of your birthday month with no gap
- Enrolling later in the Initial Enrollment Period still avoids a late penalty, but can delay your coverage start date
- Acting early gives you time to compare plans, check doctor acceptance, and review prescription coverage
How the 3-Month Rule Fits Into Your 7-Month Initial Enrollment Period
Your Initial Enrollment Period is made up of three distinct pieces: the 3 months before your birthday month, your birthday month itself, and the 3 months that follow. Together, these add up to the full 7-month window during which you can sign up for Medicare.
Medicare structures eligibility this way to give you time to prepare before you actually need coverage, while also offering flexibility if you need a bit longer to decide. This design is meant to reduce the chance of a gap between losing other coverage and starting Medicare.
Breaking the period down into these three parts can make the whole process feel far less overwhelming. Instead of thinking of enrollment as one vague deadline, you can picture it as a sequence of smaller, manageable choices.
The 3 Months Before Your Birthday Month
If you enroll during this early window, your coverage generally starts on the first day of your birthday month. For most people, this is the best time to act if the goal is seamless coverage with no waiting period.
Acting early also gives you breathing room to compare coverage options, check whether your doctors accept Medicare, and review your prescription needs before your coverage date arrives.
Your Birthday Month and the 3 Months After
Enrolling during your birthday month or in the 3 months following it is still within your Initial Enrollment Period, so you will not face a late enrollment penalty. However, the timeline for when your coverage actually begins shifts.
Waiting even a short time, such as enrolling in your birthday month instead of the month before, can push your coverage start date back. For anyone hoping to avoid a lapse between other coverage and Medicare, that shift is worth planning around.
Does It Matter When You Enroll? How Timing Affects Your Coverage Start Date
Yes, timing matters, and the difference comes down to a simple rule. If you sign up during the three months before your birthday month, your coverage begins on the first day of your birthday month.
If you enroll during your birthday month or in the three months after, your coverage instead starts the first day of the following month. That one shift, from your birthday month to the month after, is the practical heart of what people mean when they mention the 3-month rule.
Consider someone whose birthday falls in July. If they enroll in April, May, or June, their Medicare coverage would start July 1, lining up neatly with their birthday month. If instead they wait until July to sign up, coverage would not begin until August 1, and if they enroll in August, coverage would begin September 1.
This kind of timeline is especially important if you are retiring or losing other health coverage around your 65th birthday. A short delay in enrollment can translate directly into a short gap in your Medicare coverage.
I always tell people the smartest move is to enroll in the three months before your birthday month, even if you are still deciding on the rest of your coverage. Locking in your Part A and Part B start date early gives you breathing room to compare your Medigap, Medicare Advantage, or Part D options without the pressure of a looming coverage gap.
Does the 3-Month Rule Apply to Part A and Part B the Same Way?
The same 7-month window and the same coverage start rules generally apply to both Part A and Part B. Where the two parts differ is in what is actually at stake if you delay.
Most people qualify for premium-free Part A because they or a spouse paid Medicare taxes for enough years. If that applies to you, timing mostly matters for avoiding a gap in hospital coverage rather than for avoiding extra monthly costs.
Part B is different because nearly everyone pays a monthly premium for it, set at $202.90 in 2026 for most beneficiaries. Enrollment timing affects both when your coverage begins and when you start paying that premium, so it deserves just as much attention as Part A, if not more.
If you are unsure whether you qualify for premium-free Part A, it is worth confirming through the Social Security Administration before relying on assumptions about your specific costs.
Does the 3-Month Rule Apply to Special Enrollment Periods Too?
The 3-months-before and 3-months-after structure is specific to the Initial Enrollment Period tied to turning 65. It is not the same framework used for Special Enrollment Periods, such as the one available when you lose employer or union health coverage.
Special Enrollment Periods follow their own separate timing rules, which depend on factors like when your employer coverage actually ends and how your employer plan is structured. Because of that, it is a mistake to assume the same "3 months before" pattern automatically carries over.
If you are still working past 65 and covered by a group health plan, your situation likely falls under Special Enrollment Period rules rather than the standard Initial Enrollment timeline. Confirming your specific circumstances, rather than guessing based on what applies to someone else, is the safest way to avoid a timing mistake.
What Happens If You Miss the 3 Months Before Your Birthday Month?
Missing the early window is not the end of your options. You can still enroll during your birthday month or in the 3 months that follow, since both fall within your 7-month Initial Enrollment Period. The tradeoff, as covered earlier, is a later coverage start date.
If you miss the entire 7-month window without qualifying for a Special Enrollment Period, you will generally need to wait for the General Enrollment Period to sign up. This can mean a longer gap before your coverage begins.
Watch for Late Enrollment Penalties
Delaying Part B enrollment beyond your Initial Enrollment Period, without qualifying coverage elsewhere, can lead to a late enrollment penalty. This penalty adds 10% to your monthly Part B premium for each full 12-month period you waited, which comes to $202.90 added to the standard premium in 2026 for a full 12-month delay.
The goal in laying this out is not to create alarm, but to show why acting during the early part of your window tends to be the simplest path. Enrolling before your birthday month removes the guesswork and keeps your coverage timeline predictable.
How to Use This Timeline to Choose Coverage With Confidence
As soon as you know your birthday month, mark your personal 7-month window on a calendar. Having those dates in front of you turns an abstract deadline into something concrete you can plan around.
Use the months before your birthday month to compare coverage options, confirm that your preferred doctors are in network, and review whether your current prescriptions are covered under the plans you are considering. This is the same window that gives you the earliest possible coverage start date, so it does double duty.
Confirm your exact birthday month window with Social Security or Medicare directly
Compare Medigap, Medicare Advantage, and Part D options before your coverage start date
Check that your doctors and prescriptions are covered under any plan you are considering
Speak with a licensed Medicare agent to confirm your specific dates without pressure
A licensed Medicare agent can walk through your specific dates and coverage options with you, answering questions without pushing you toward a decision before you are ready.
Frequently Asked Questions About the Medicare 3-Month Rule
What is the 3 month rule for Medicare enrollment?
I'm not ready to decide yet. How much time do I actually have?
Will I get a pushy sales call if I ask about my enrollment dates?
Can I just figure out my enrollment dates on my own?
How do I know which Medicare information online I can trust?
What if I enroll and later regret my coverage choice?
Does the 3 month rule apply if I'm still working past 65?
What happens to my coverage start date if I wait until my birthday month to enroll?
Your Next Step: Mark Your Window and Get Personalized Guidance
The core idea behind the 3-month rule is simple: the 3 months before your birthday month is generally your best window to enroll if you want coverage to begin without delay. Knowing this single detail can shape how you plan the rest of your Medicare decisions.
If you want to confirm your exact dates or talk through how your specific situation lines up with these rules, a licensed Medicare agent can walk through your options with you and help you compare plans with confidence.
Related Articles
Have Medicare questions?
Our licensed Medicare agents are available to help you find the right coverage.